Most of the preffered stock prevent dividends from being paid on common stock until all preferred stock dividends are paid which includes previous and current dividends.
Showing posts with label Finance. Show all posts
Showing posts with label Finance. Show all posts
Thursday, 12 June 2014

Wednesday, 11 June 2014
Junk Bonds
It is a non Investment grade bond. These type of bonds carry a rating of BB(High Risk) or lower by S&P. It has higher default risk as compared to investment grade bonds. Since the risk is very high, they offer higher yield to the bondholders than safer bonds.
Junk Bonds: "High Risk - High Return" compared to Safer Bonds
Thursday, 29 May 2014
Consumer Price Index
CPI - Consumer Price Index
- A measure that examines the weighted average of prices of a basket of consumer goods and services.
- It is calculated by taking price changes for the items which are predetermined.
- CPI is one of the most frequently used statistics for identifying periods of inglation or deflation.
Wednesday, 21 May 2014
Bonds
-------BONDS----------
What is bond?
ANS: It is a long term debt obligation where the bondholder get interst, and at maturity the bondholder get the princpal amount.
Who issues bonds?
ANS: Primary investors are institutional investors such as commercial banks, bond mutual funds, pension funds, and insurance companies.
Maturities of Bonds?
ANS: Most bonds have maturities of 10 to 30 years.
What types of Bonds are there?
ANS:
- Fixed Rate Bonds
- Convertible Bonds
- Floating Rate notes
- High Yield Bonds
- Zero Coupon Bonds
- Inflation Linked Bonds
- Discount Bonds
- Asset Backed Securities
- Perpetual Bonds
- Municipal Bonds
Terms used in BONDS
- Coupon Rate
- Face/Par/Maturity value
- Maturity
What are the characteristics of Corporate Bonds?
ANS:
- Sinking Fund Prvision
- Protective Covenants
- Call Provision
- Bond Collateral
- Low and Zero Coupon Bonds
- Variable-Rate Bonds
- Convertibility
RATIO ANALYSIS
FINANCIAL RATIO ANALYSIS
Profitability Ratios
Profit MarginProfit Margin = (Net Income/Sales)
Return on Assets
Return on assets = (Net Income/Total Assets)
Return on Equity
Return on Equity = (Net Income/Total Equity)
Asset Utilization Ratios
Return on Equity = (Net Income/Total Equity)
Asset Utilization Ratios
Receivables Turnover
Average Collection Period
Inventory Turnover
Fixed Asset Turnover
Total Asset Turnover
Average Collection Period
Inventory Turnover
Fixed Asset Turnover
Total Asset Turnover
Liquidity Ratios
Current Ratio
Current Ratio = (Current Assets/Current Liabilites)
Quick Ratio
Quick Ratios = (Current Assets-Inventories)/Current Liabilities
Super Quick Ratio
Super Quick Ratio = Cash/Current Liabilities
Debt Utilization Ratios
Debt to total assets
times interest earned
Fixed charged coverage
Current Ratio
Current Ratio = (Current Assets/Current Liabilites)
Quick Ratio
Quick Ratios = (Current Assets-Inventories)/Current Liabilities
Super Quick Ratio
Super Quick Ratio = Cash/Current Liabilities
Debt Utilization Ratios
Debt to total assets
times interest earned
Fixed charged coverage
Net Present Value

NPV(Net Present Value) is the difference between inflows(money coming in) and outflows(money going out) in Present value.
How to calculate it?????
1) Find out the outflow or the investment cost. For say. tk.100
2) Find out the inflow or income that the project will generate in the coming years say Tk.50 in the 1st year then again Tk 50 in the 2nd year and again taka 50 in the 3rd year.
3) Find out the discount rate say 10%.
4) Now convert the future inflows in the Present value.
5) Take the present value of inflows and outflows and subtract the inflows from outflows i.e the NPV(NeT Present Value).
Now using the given information above we will solve it using this formula.

Ct = Inflows = Tk.50 for 3 years
C0 = Outflows = 100
r = discount rate = 10%
t =number of years
NPV = -100+ 50/1.10 + (50/1.10^2) + (50/1.10^3)
NPV=Tk.24.34.
If it forms an annuity(Equal amount and equal interval) like the above example then you can use this formula.
NPV = -C0- Ct(PVIFA r,t)
NPV = -100-50(PVIFA 10%,3)
NPV = TK.24.34
Accept Reject Criterion
Accept the project when NPV=>0
Reject the project when NPV<0
(PVIFA = Present Value Interest Factor of Annuity)
Saturday, 17 May 2014
Letter of Credit
Letter of Credit (L/C)
It is a document issued by a financial institution that provides guaranttee of payment to the seller on behalf of the buyer.
It is a document issued by a financial institution that provides guaranttee of payment to the seller on behalf of the buyer.
Factors Affecting Exchange Rates
- Differential Interest Rates
- DIfferential Interest Rates
- Government Intervention
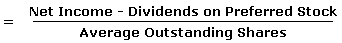
Earnings Per Share (EPS)
Earnings Per Share
The portion of a company's profit allocated to each outstanding share of common stock. Earnings per share serves as an indicator of a company's profitability.
This is a portion of an Income Statement of a bank.


Straight Line Depreciation
Straight Line Depreciation
Example: For $5 million, Company XYZ purchased a machine that will have an estimated useful life of five years. The company also estimates that in five years, the company will be able to sell it for $500,000 for scrap parts.

Depreciation Expense = ($5,000,000 - $500,000)/5
Depreciation Expense = $900,000
Example: For $5 million, Company XYZ purchased a machine that will have an estimated useful life of five years. The company also estimates that in five years, the company will be able to sell it for $500,000 for scrap parts.
Depreciation Expense = ($5,000,000 - $500,000)/5
Depreciation Expense = $900,000
Friday, 16 May 2014
Subscribe to:
Posts (Atom)